
Pemo’s in-principle approval from the Central Bank of the UAE supports broader financial services for SMEs as fintech enters a more regulated growth phase.
T he UAE’s fintech sector is entering a more regulated phase as financial technology companies look to expand their services to small and medium-sized businesses while meeting higher expectations around governance and compliance.
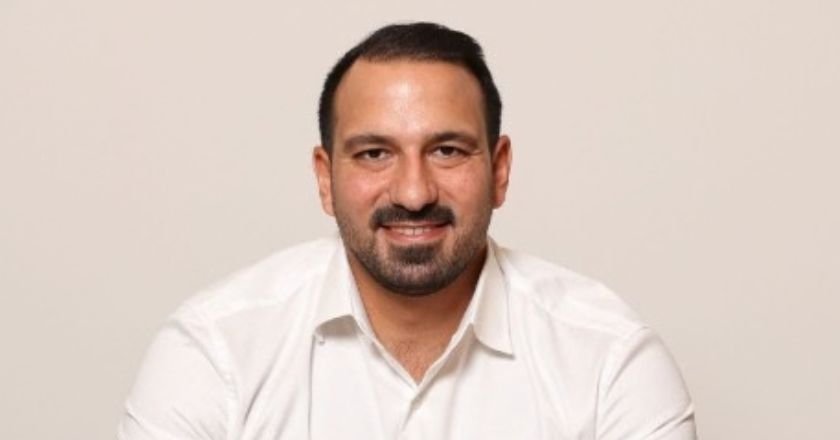
For fintech firms operating in the country, the shift is creating an environment where regulatory approval is becoming increasingly important to expanding the range of financial products available to businesses. Pemo, a UAE-based spend management platform, recently received in-principle approval from the Central Bank of the UAE, which co-founder and CEO Ayham Gorani says will allow the company to broaden its offering to SMEs.
“The in-principle approval matters most for what it lets us build. It puts Pemo on firmer ground to expand the products we offer SMEs, under a framework regulators and customers can trust,” Gorani said. “For the wider market it signals something important too: fintech in the UAE is maturing past the ‘move fast’ era into one built on governance and durability, and we want to help lead that shift.”
Pemo, which says more than 7,000 companies use its platform, has expanded its offering with a business account launched with ruya and an MCP release that allows finance teams to query Pemo through tools they already use.
Gorani said the company’s growth since 2022 has been driven by its focus on the day-to-day financial challenges facing UAE SMEs, but that its next phase would focus more on expanding services to existing customers.
“Proximity to the problem, and a team that owns outcomes without waiting to be told. We built Pemo around what UAE SMEs actually deal with day-to-day, and today more than 7,000 companies run their spend through the platform,” he said.
“What comes next is depth rather than breadth. Our in-principle approval from the CBUAE lets us widen what we offer the same customers. We’ve launched the business account with ruya, we ship product weekly, and our recent MCP release means a finance team can query Pemo from whatever tool they already work in.”
Challenges of cash flow
For SMEs, however, one of the biggest financial challenges remains having a clear view of cash flow, particularly as businesses deal with VAT, corporate tax, reporting requirements and the introduction of e-invoicing.
“Cash flow visibility is still the biggest headache. Between VAT, corporate tax, reporting requirements and e-invoicing on the horizon, a small finance team spends 40 to 60 hours a week on admin that does nothing to move the business forward,” Gorani said. “Large companies absorb that with headcount, but SMEs cannot. So we’re building the finance function SMEs cannot afford to hire.”
“Receipts match automatically, expenses code themselves to the right account, and month-end close drops from seven days to three hours. The founder sees where the money stands today rather than three weeks after the fact,” he added.
UAE drives real momentum
Gorani said the UAE’s ability to attract and support fintech companies has also been helped by its regulatory environment, although he pointed to differences between Gulf markets as a challenge for regional expansion.
“The UAE has built real momentum by making it straightforward to license, bank and scale a fintech here, and regulators have been willing to move with the market rather than behind it,” he said.
“What still needs work is consistency across the wider Gulf. A licence or product that works cleanly in the UAE can still hit friction the moment you look at Saudi Arabia or Bahrain, and closing that gap would let regional fintechs grow faster.”
The shift towards automation is also changing how fintech companies structure their own operations. Gorani said Pemo has maintained a relatively lean workforce, with employees expected to take responsibility across multiple functions.
“We typically hire all-rounders. At our stage, someone who can run a campaign and also take a customer call is worth more than two specialists whose skillset is more narrow. We’re proud of having a flat structure, so people sit close to customers and close to the decision,” he said.
AI has become part of that model, with Pemo deploying AI agents and skills across different functions. The company has about 80 employees serving its customer base, according to Gorani.
“But AI is what makes the arithmetic work. We deploy agents and skills across every function, which is how 80 people serve 7,000 customers — and growing,” he said. “From 2024 to 2026 we have seen an increase of revenue of 3.15x per head. This is a number that we closely monitor as it shows the discipline of the team to grow efficiently.”
Pemo has raised $19 million from investors including Cherry Ventures, Shorooq Partners, Augmentum Fintech and Speedinvest. Gorani said the fundraising experience also changed how he thinks about building the company.
“If I could go back, I’d tell myself that validation matters more than conviction. It’s easy to fall in love with an idea and assume the market will follow, but investors and customers respond to proof,” he said.
“Fundraising rewards discipline. Raising our seed with Cherry Ventures and Shorooq Partners, and building from there with Augmentum Fintech and Speedinvest, taught me to raise for the milestone in front of us rather than chase a number for its own sake.”
Source: Tahawul Tech
